


AleaSoft Energy Forecasting, November 9, 2026. In the first week of November, prices rose across the main European electricity markets, driven by higher demand and lower solar energy production, despite declining gas prices. Italy, France, Spain and Portugal registered their highest daily prices since 2022. Meanwhile, solar photovoltaic energy production reached all‑time records for a November day in the Iberian Peninsula and Germany. TTF gas and Brent oil futures fell amid expectations of diplomatic progress between the United States and Iran.
Solar photovoltaic and wind energy production
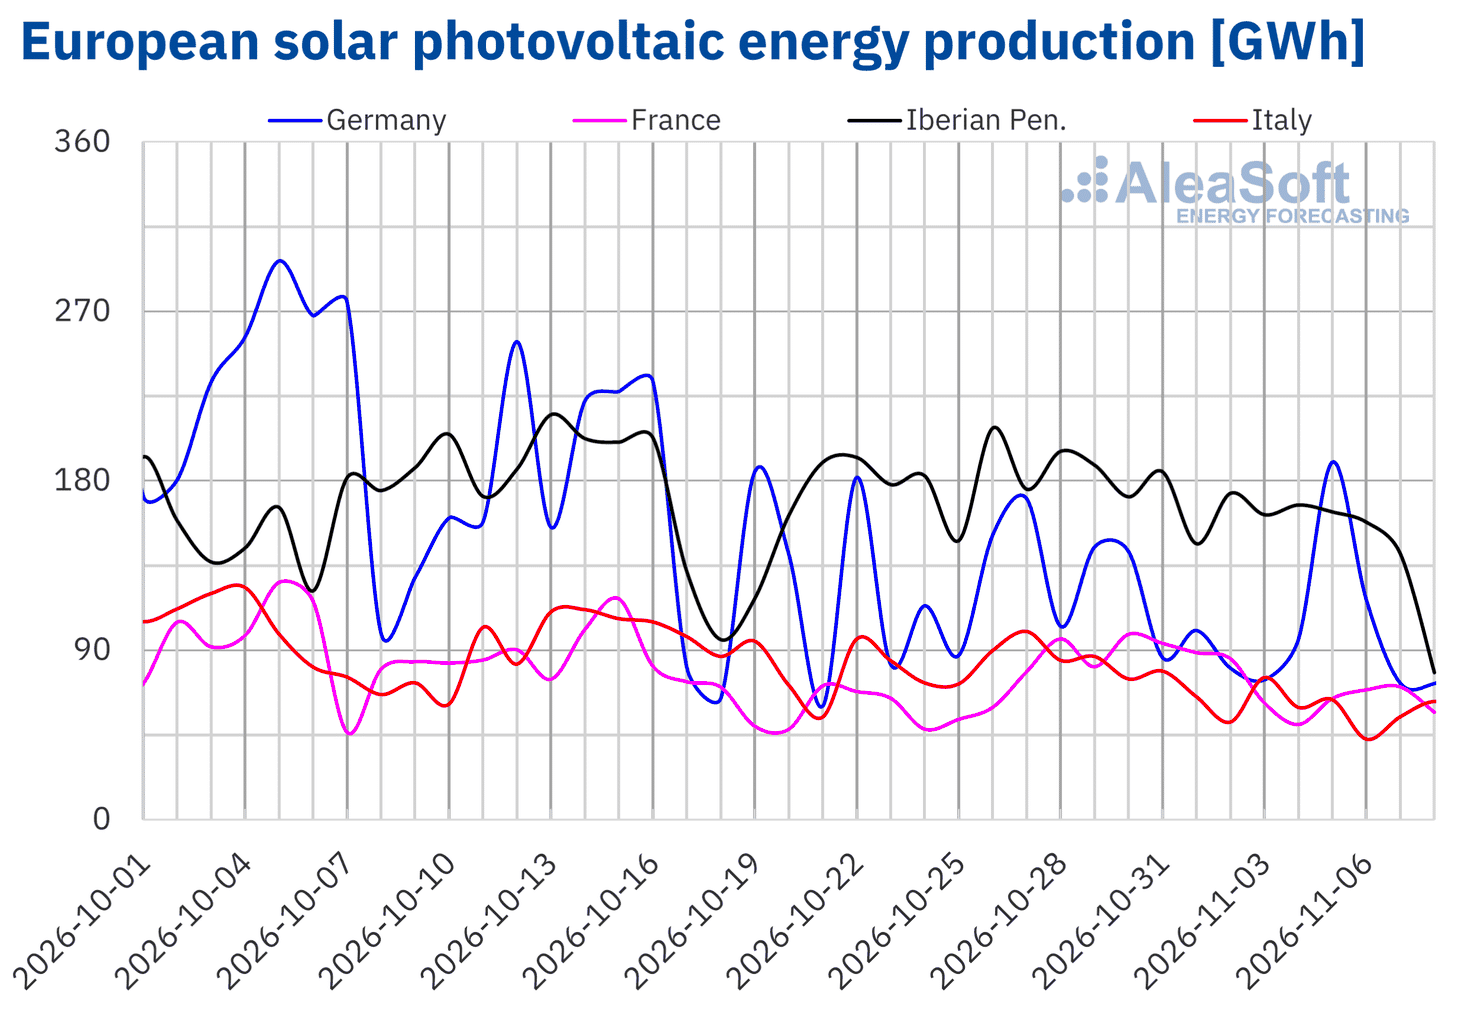
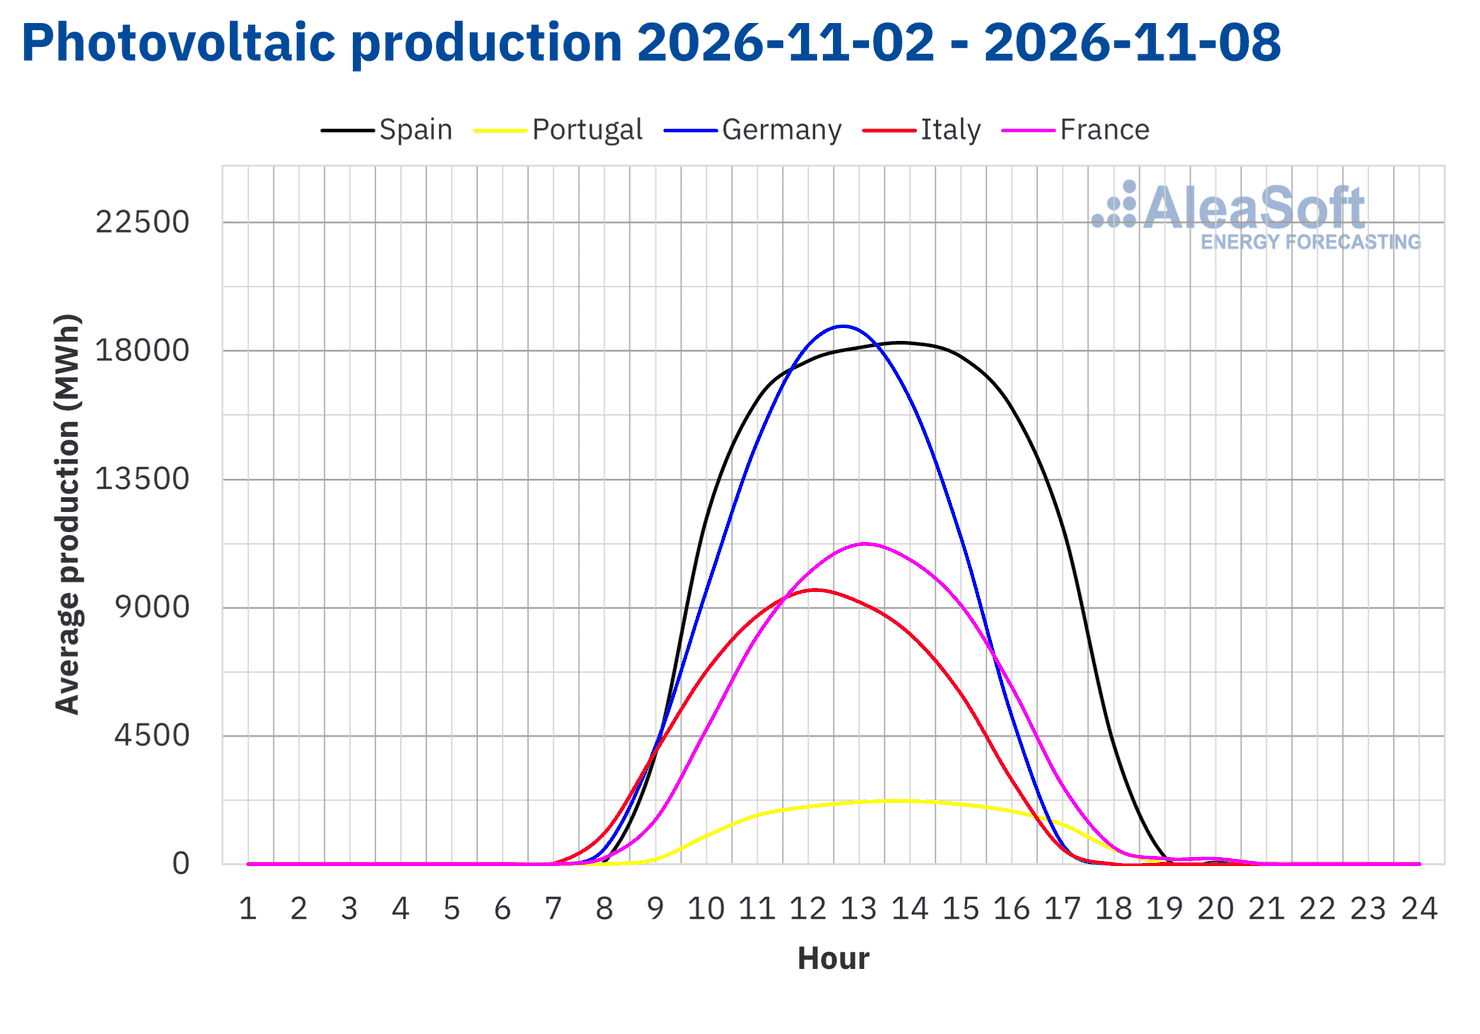
During the first week of November, solar photovoltaic energy production declined in the main European electricity markets compared to the previous week, following increases in the last week of October. Italy registered the largest drop, at 29%, followed by France, with a 23% decrease, and Germany, with 22%. Production fell by 21% in Portugal, while Spain registered the smallest decline, at 18%.
Despite the weekly decline, Spain, Portugal and Germany set all‑time solar photovoltaic energy production records for a November day. On November 2, Spain generated 156 GWh, while Portugal reached 22 GWh on November 4 and Germany registered 190 GWh on November 5.
For the week of November 9, AleaSoft Energy Forecasting’s solar energy forecasts indicate production declines in the German, Spanish and Italian markets.
 Source: Prepared by AleaSoft Energy Forecasting using data from ENTSO-E, RTE, REN, Red Eléctrica and TERNA.
 Source: Prepared by AleaSoft Energy Forecasting using data from ENTSO-E, RTE, REN, Red Eléctrica and TERNA.
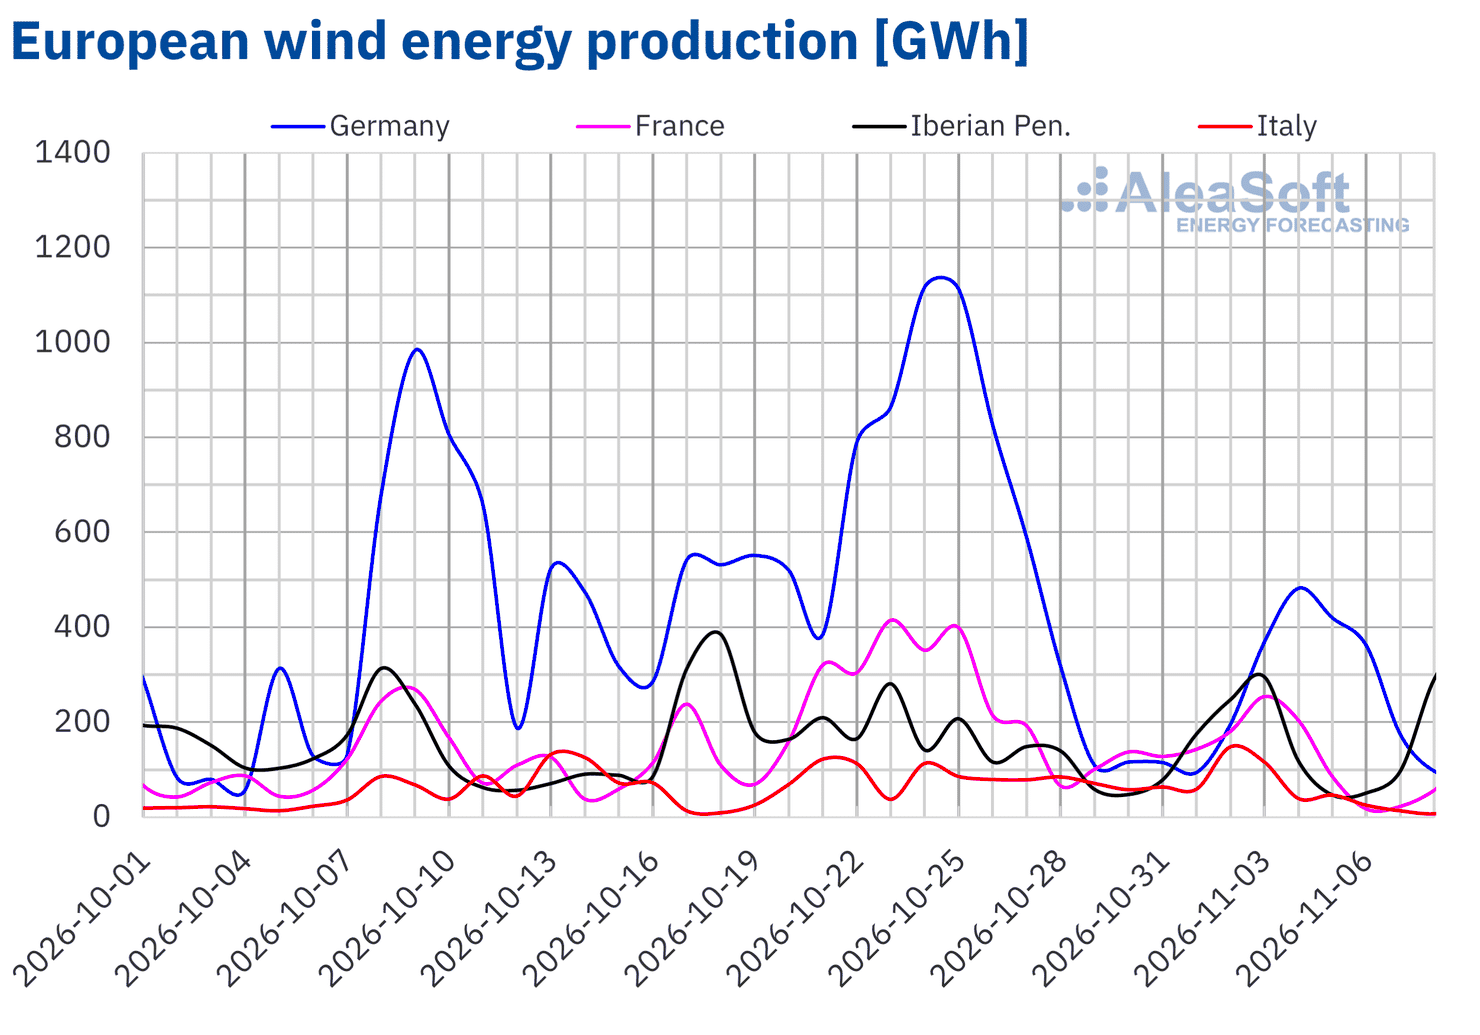
During the first week of November, wind energy production increased in the Iberian Peninsula compared to the previous week, following declines in the last week of October. Portugal registered the largest increase, at 348%, while Spain registered a 25% rise. In contrast, Italy, France and Germany registered their second consecutive week of declines. Italy registered the largest drop, at 20%, followed by France, with 16%, and Germany, with 3.1%.
For the week of November 9, AleaSoft Energy Forecasting’s wind energy forecasts indicate increases in production in the Spanish, Portuguese, Italian and French markets. In contrast, wind energy production will decline in the German market.
 Source: Prepared by AleaSoft Energy Forecasting using data from ENTSO-E, RTE, REN, Red Eléctrica and TERNA.
Electricity demand
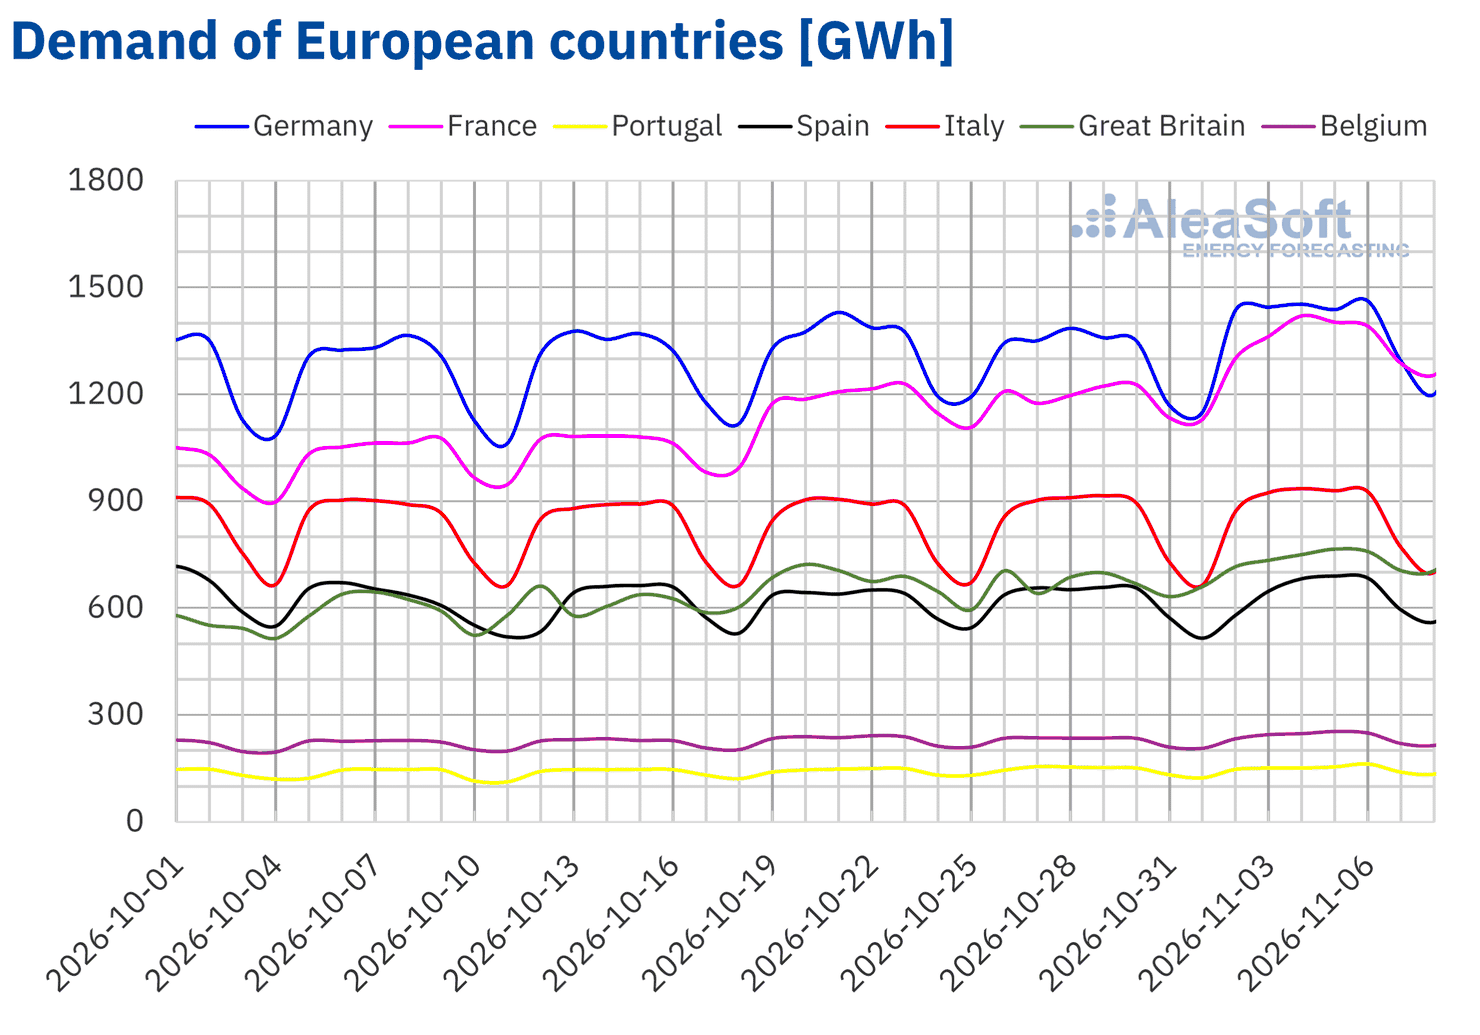
During the first week of November, electricity demand increased in the main European electricity markets compared to the previous week. France registered the largest increase, at 14%, marking its sixth consecutive week of growth. Great Britain followed with a 9.5% rise and Germany with 6.8%. In Belgium, demand grew by 4.5%. These three markets reversed the declines of the previous week. Meanwhile, Italy registered a 3.1% increase, marking its third consecutive week of growth. Portugal, with a 2.6% increase, registered its fourth consecutive week of growth, while Spain, with a 2.1% rise, accumulated three consecutive weeks of increases. In Spain, the observance of the All Saints’ Day holiday on Monday, November 2, in several autonomous communities may have moderated demand growth.
During the week, average temperatures fell in the markets under analysis compared to the previous week, contributing to higher demand. France registered the largest drop, at 3.5 °C, followed by Belgium, with 3.3 °C, and Spain, with 3.2 °C. In Great Britain, Portugal, Germany and Italy, the declines ranged from 3.1 °C in Great Britain to 1.4 °C in Italy.
For the week of November 9, AleaSoft Energy Forecasting’s demand forecasts indicate increases in the British and Italian markets. In contrast, demand will decline in the French, Belgian, German, Portuguese and Spanish markets. In Belgium, the Armistice Day holiday on Wednesday, November 11, could contribute to the forecast decline.
 Source: Prepared by AleaSoft Energy Forecasting using data from ENTSO-E, RTE, REN, Red Eléctrica, TERNA, National Grid and ELIA.
European electricity markets
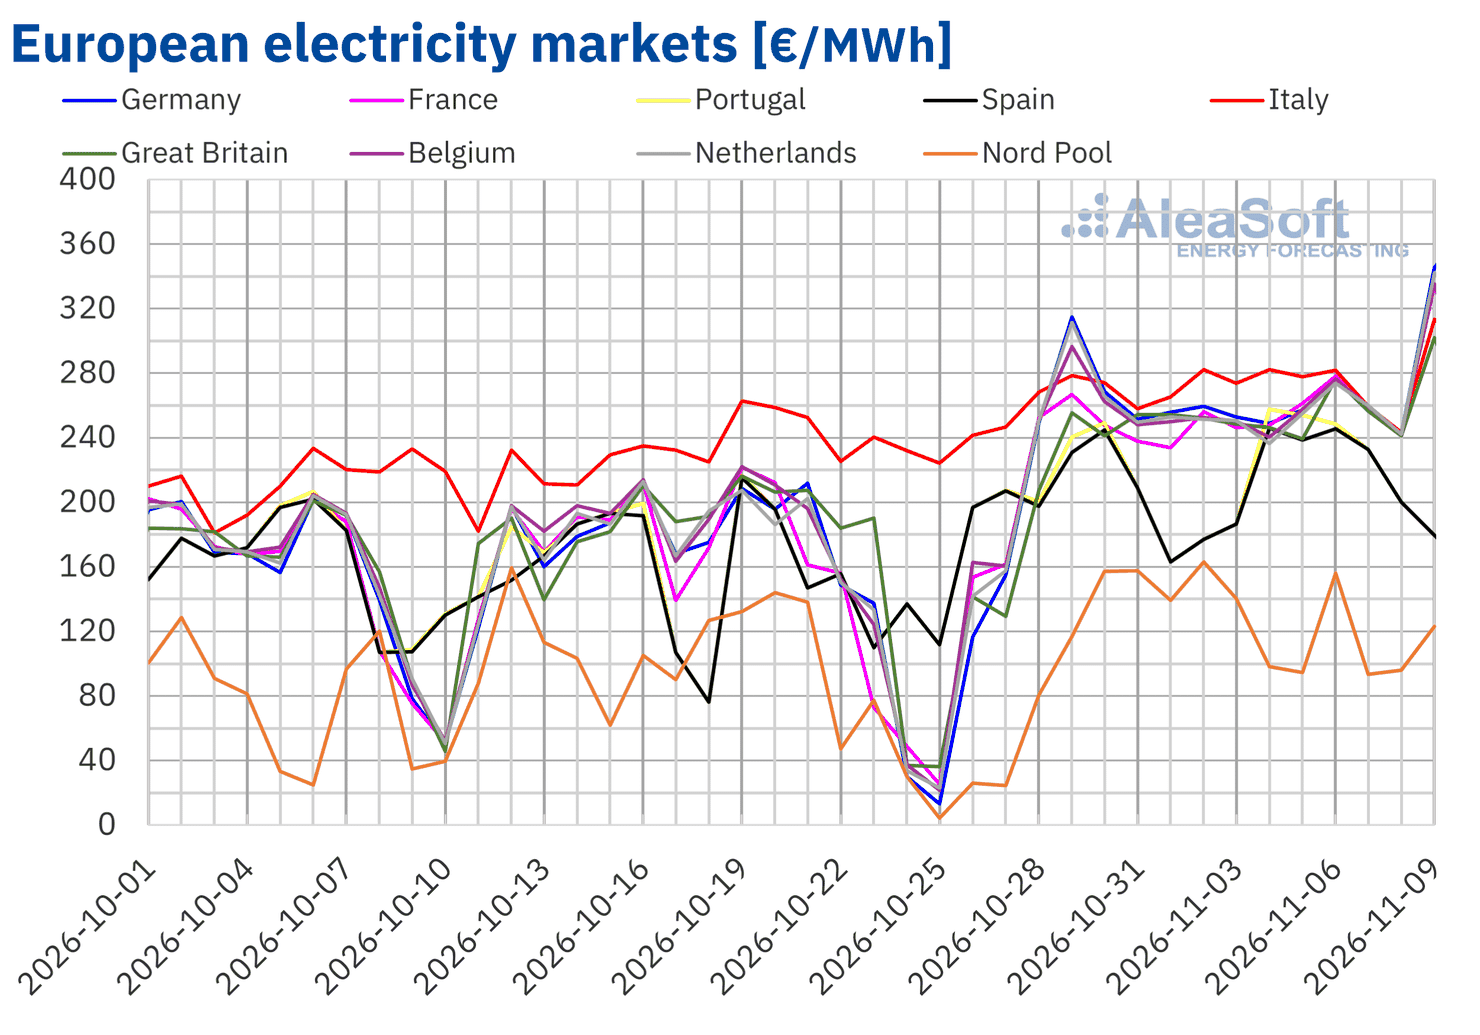
Weekly average prices in the main European electricity markets increased during the first week of November compared to the previous week. The Nordic market registered the largest increase, at 20%, followed by the British market, with a 19% rise, and the French market, with 15%. Prices also increased by 11% in Germany, 9.1% in Belgium and 8.6% in the Netherlands. The Portuguese and Spanish markets registered increases of 6.2% and 5.3%, respectively, while the Italian market registered the smallest rise, at 3.7%.
The Italian market once again registered the highest weekly average price, at €271.46/MWh, while the Nordic market registered the lowest, at €120.19/MWh. In the remaining markets analyzed at AleaSoft Energy Forecasting, weekly average prices exceeded €200/MWh, ranging from €218.07/MWh in Spain to €256.59/MWh in Germany.
Regarding daily prices, on Monday, November 2, the Italian market reached €282.30/MWh, the highest price of the week among the markets under analysis. According to data analyzed at AleaSoft Energy Forecasting, this was the market’s highest price since December 17, 2022. On the same day, the Nordic market reached its weekly high of €162.99/MWh. On November 4, the Portuguese and Spanish markets reached their highest prices of the week, at €257.55/MWh and €246.01/MWh, respectively. For Portugal, this was the highest price since April 6, 2022, and for Spain, since April 7, 2022. On Friday, November 6, the remaining markets registered their weekly highs. That day, the French market reached €278.29/MWh, its highest price since December 18, 2022, while the British market reached €276.50/MWh, its highest price since January 23, 2025. The Belgian, German and Dutch markets registered prices of €276.47/MWh, €275.64/MWh and €273.90/MWh, respectively.
On Monday, November 9, prices exceeded €300/MWh in the German, French, Italian, British, Belgian and Dutch markets, surpassing the highs of the previous week. The German market reached €345.64/MWh and the Dutch market €342.43/MWh, their highest prices since December 13, 2024. Prices in the Belgian, French and Italian markets reached €335.27/MWh, €334.12/MWh and €313.51/MWh, respectively. These were their highest prices since December 17, 2022. The British market registered a price of €301.95/MWh, its highest price since January 23, 2025. Meanwhile, the Nordic market registered the lowest price of the week among the markets under analysis, at €93.62/MWh, on Saturday, November 7. The Spanish and Portuguese markets registered their weekly lows of €177.06/MWh in both cases on Monday, November 2. With the exception of the Nordic market and the first two days of the week in the Iberian market, daily prices remained above €200/MWh throughout the week.
Higher demand across all markets, supported by falling temperatures, and lower solar energy production drove prices upward. In Germany, France and Italy, declining wind energy production also contributed to the increases. In contrast, lower TTF gas prices moderated the rises. In Spain and Portugal, higher wind energy production in the Iberian Peninsula also limited price increases.
AleaSoft Energy Forecasting’s price forecasts indicate that prices will decline in the Spanish, Portuguese, French, British and Belgian markets during the week of November 9, supported by higher wind energy production in the Iberian Peninsula and France, as well as lower demand in France, Belgium and Spain. In contrast, prices will increase in the Dutch, Italian and German markets. In Germany, declining wind energy production will contribute to the rise.
 Source: Prepared by AleaSoft Energy Forecasting using data from OMIE, RTE, Nord Pool and GME.
Brent, fuels and CO2
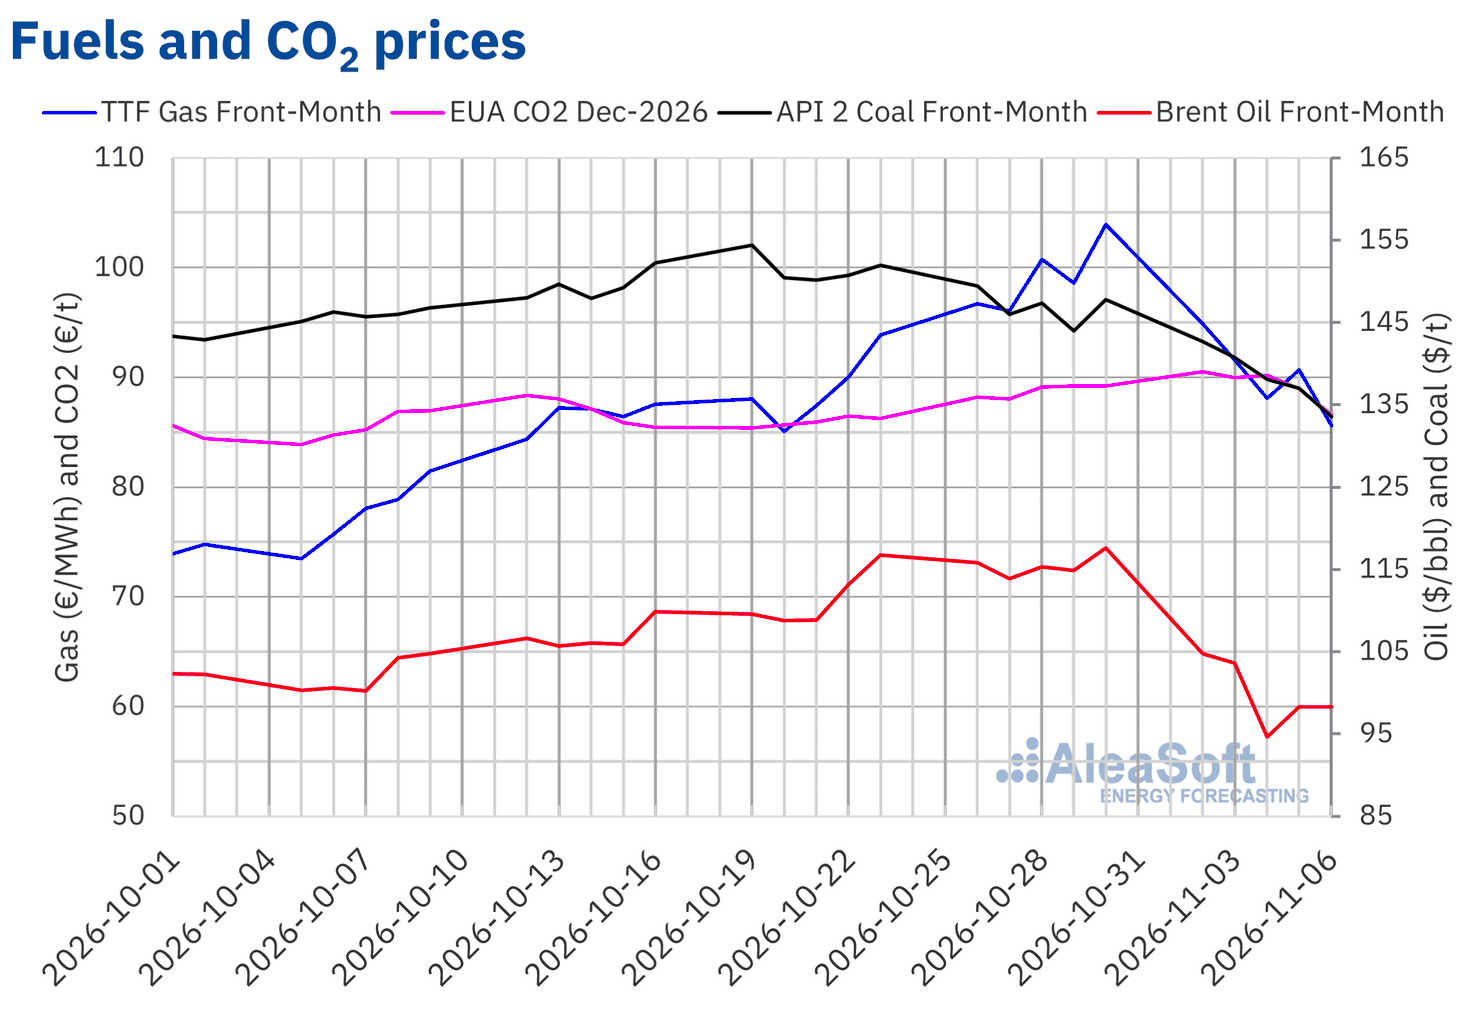
Brent oil futures for the Front‑Month in the ICE market reached their weekly maximum settlement price of $104.77/bbl on Monday, November 2. This price was already 11% lower than the previous Friday’s level. On November 4, following an 8.7% decline compared to the previous day, these futures registered their weekly minimum settlement price of $94.62/bbl. According to data analyzed at AleaSoft Energy Forecasting, this was the lowest price since September 1. Prices partially recovered during the last two trading sessions of the week. On Friday, November 6, the settlement price stood at $98.32/bbl, 16% lower than the previous Friday.
Expectations of an agreement between the United States and Iran to end the war put downward pressure on prices throughout the week. Reports of a draft agreement and Iran’s submission of a nuclear proposal to Washington through Qatar contributed to this. In addition, OPEC+ decided on November 1 to maintain its oil production targets for December without changes. However, attacks and incidents involving oil tankers in and around the Strait of Hormuz continued during the week, and the risk of another military escalation following the US midterm elections remained a concern for the market.
As for TTF gas futures in the ICE market for the Front‑Month, they reached their weekly maximum settlement price of €94.86/MWh on Monday, November 2. This price was already 8.7% lower than the previous Friday’s level. Prices declined through November 4 and, after a 2.9% increase on Thursday, November 5, fell again on Friday, November 6. That day, these futures reached their weekly minimum settlement price of €85.59/MWh. According to data analyzed at AleaSoft Energy Forecasting, this was the lowest price since October 21 and 18% lower than the previous Friday.
Expectations of diplomatic progress between the United States and Iran also contributed to lower gas prices. However, LNG supplies from Qatar remained limited after the country extended the force majeure declaration on its exports through the end of December. In addition, European Union gas storage levels stood at 74.6% of capacity on November 1, below the 82.8% level a year earlier.
Regarding CO2 emission allowance futures in the EEX market for the reference contract of December 2026, they reached their weekly maximum settlement price of €90.53/t on Monday, November 2. According to data analyzed at AleaSoft Energy Forecasting, this price was 1.5% higher than the previous Friday’s level and the highest since January 17. Prices subsequently declined in three of the remaining four trading sessions. On Friday, November 6, they registered their weekly minimum settlement price of €86.55/t, the lowest since October 24 and 3.0% lower than the previous Friday.
 Source: Prepared by AleaSoft Energy Forecasting using data from ICE and EEX.
AleaSoft Energy Forecasting’s analysis on the prospects for energy markets in Europe
On Thursday, November 12, AleaSoft Energy Forecasting will hold the 71st edition of its monthly webinar series. This edition will focus on battery energy storage and hybridization, technologies that continue to gain importance as new projects move forward and the electricity system requires greater flexibility. The speakers will discuss battery profitability and revenue streams, paying particular attention to Spain’s new capacity market, as well as the key factors for analyzing and valuing energy storage and hybridization projects. The session will also review how Europe’s most relevant energy markets have evolved in recent weeks and what to expect during winter 2026‑2027. Luis Marquina de Soto, president of AEPIBAL, the Spanish Business Association of Batteries and Energy Storage, will participate in the webinar in Spanish for the fourth consecutive year. Oriol Saltó i Bauzà, Associate Partner at AleaSoft, will join him. Both speakers will also take part in the panel discussion, which will take place exclusively during the Spanish‑language webinar.
Source: AleaSoft Energy Forecasting.