


AleaSoft Energy Forecasting, September 28, 2026. In the fourth week of September, weekly prices rose in most major European electricity markets, driven by a drop in wind energy production despite lower gas prices. Italy was the exception, as higher wind energy production and lower demand pushed prices down. The British market registered its highest daily price since January 2025. TTF gas futures settled 9.4% below the previous week’s level, while Brent futures ended the week slightly higher.
Solar photovoltaic and wind energy production
During the week of September 21, solar photovoltaic energy production increased in most major European electricity markets compared to the previous week. Germany registered the largest increase, at 18%, followed by France, with a 5.9% rise, and Italy, with 3.9%. In Spain, production increased by 0.9%. All four markets reversed the downward trend of the previous two weeks. In contrast, Portugal registered a 4.9% decline, marking its second consecutive week of decreases.
For the week of September 28, AleaSoft Energy Forecasting’s solar energy forecasts indicate a production increase in the Italian market and declines in the German and Spanish markets.
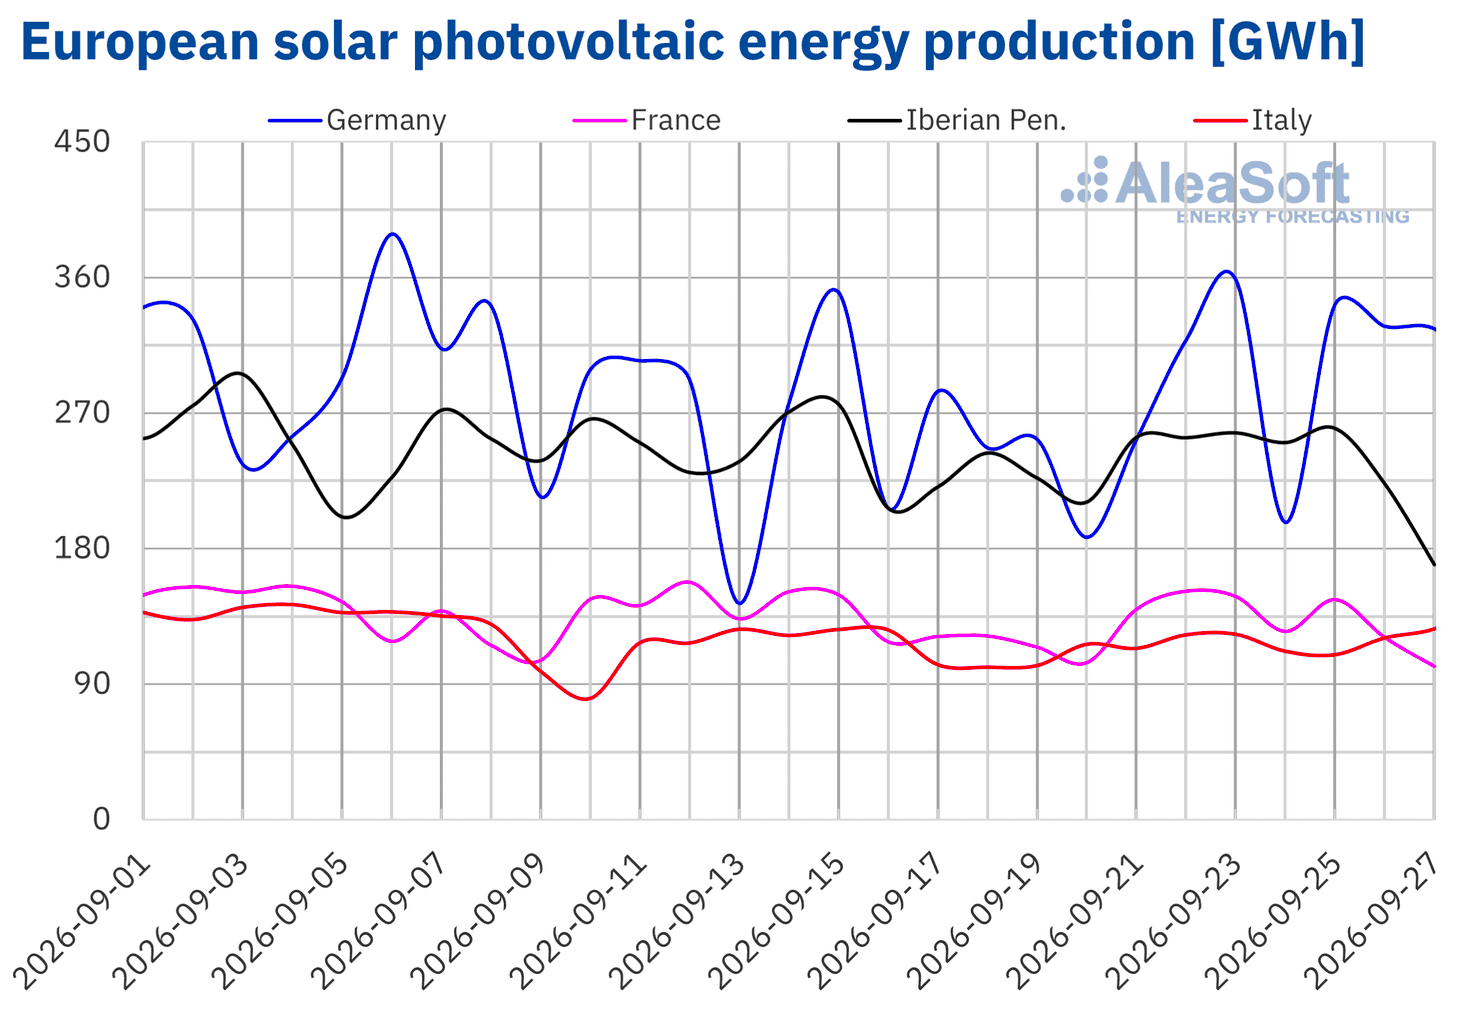 Source: Prepared by AleaSoft Energy Forecasting using data from ENTSO-E, RTE, REN, Red Eléctrica and TERNA.
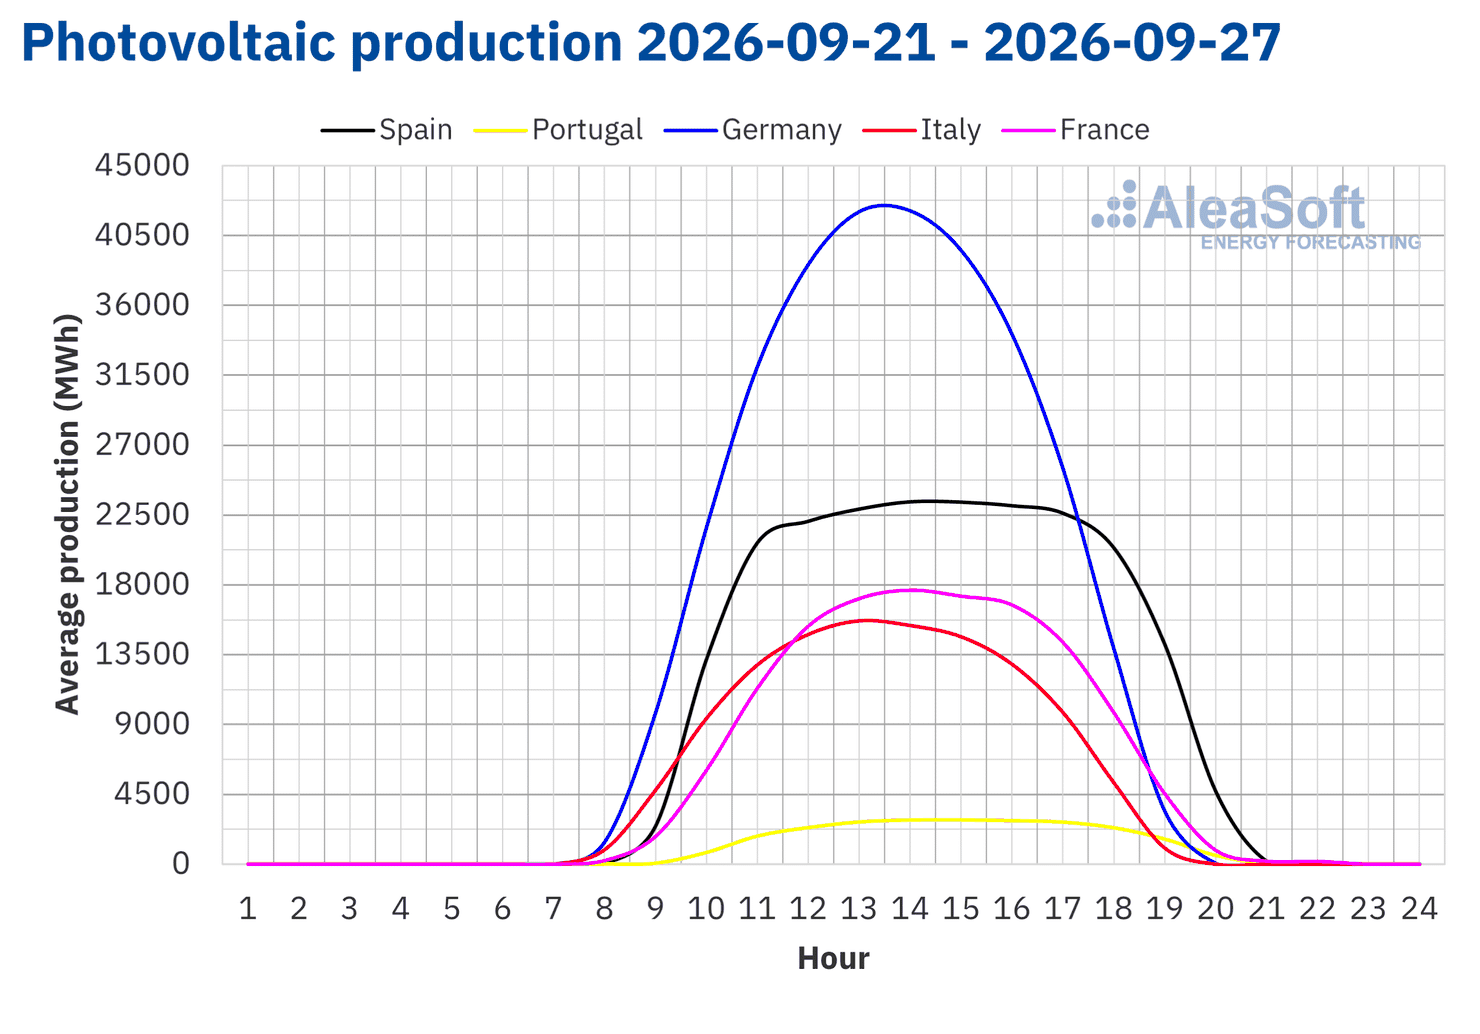 Source: Prepared by AleaSoft Energy Forecasting using data from ENTSO-E, RTE, REN, Red Eléctrica and TERNA.
In the fourth week of September, wind energy production declined in most major European electricity markets compared to the previous week. Portugal registered the largest decrease, at 54%, followed by Germany, with a 36% drop. Production fell by 30% in France and 27% in Spain. All four markets reversed the increases of the previous week. In contrast, Italy registered a 68% increase following the previous week’s decline.
For the week of September 28, AleaSoft Energy Forecasting’s wind energy forecasts indicate production increases in the French, Portuguese and Spanish markets. In contrast, wind energy production will decline in the German and Italian markets.
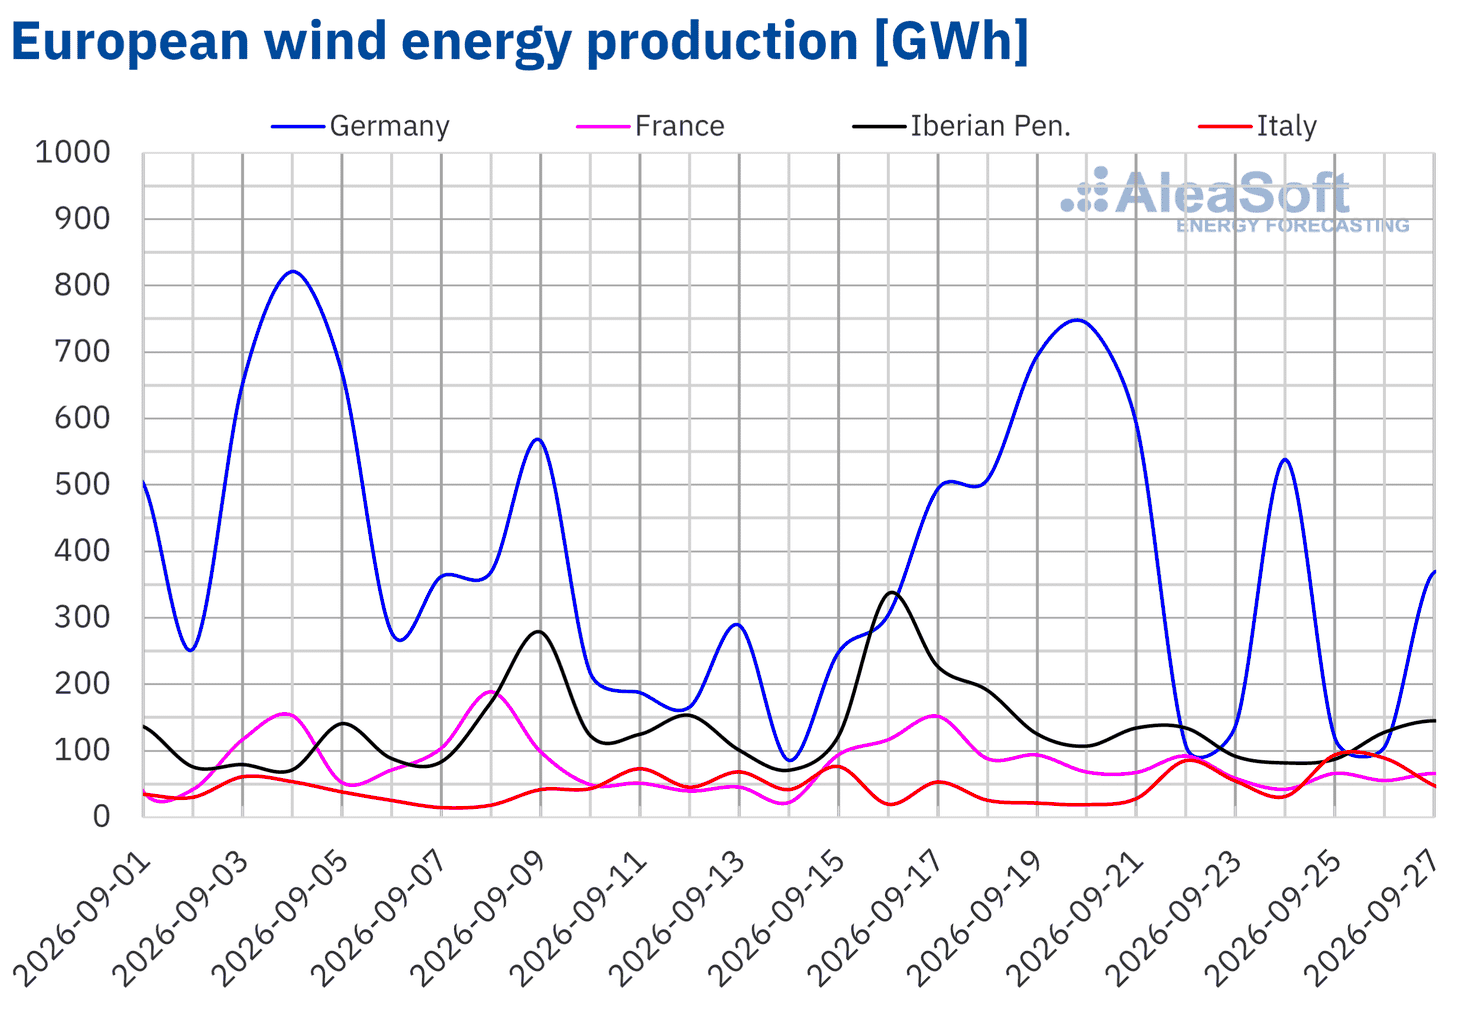 Source: Prepared by AleaSoft Energy Forecasting using data from ENTSO-E, RTE, REN, Red Eléctrica and TERNA.
Electricity demand
During the week of September 21, electricity demand declined in most major European electricity markets compared to the previous week. Italy registered the largest decrease, at 3.7%, followed by Belgium, with a 3.5% drop. In Germany, demand fell by 2.2% after four consecutive weeks of increases. France and Spain registered the smallest declines, at 0.9% and 0.2%, respectively. Italy, France and Spain thus registered their third consecutive week of declining demand.
In contrast, demand increased in Great Britain and Portugal. The British market registered the largest increase, at 5.3%, following the previous week’s decline. In Portugal, demand grew by 1.2%, marking its fourth consecutive week of increases.
During the week, average temperatures fell in most of the markets under analysis compared to the previous week. Germany registered the largest drop, at 3.1 °C, followed by Italy, with a 2.1 °C decline, and Belgium, with 1.9 °C. Temperatures fell by 0.8 °C in France and Great Britain. In contrast, they rose by 1.2 °C in Portugal and 0.8 °C in Spain.
For the week of September 28, AleaSoft Energy Forecasting’s demand forecasts indicate increases in the Portuguese, British, Belgian and French markets. In contrast, demand will decline in the Italian, Spanish and German markets.
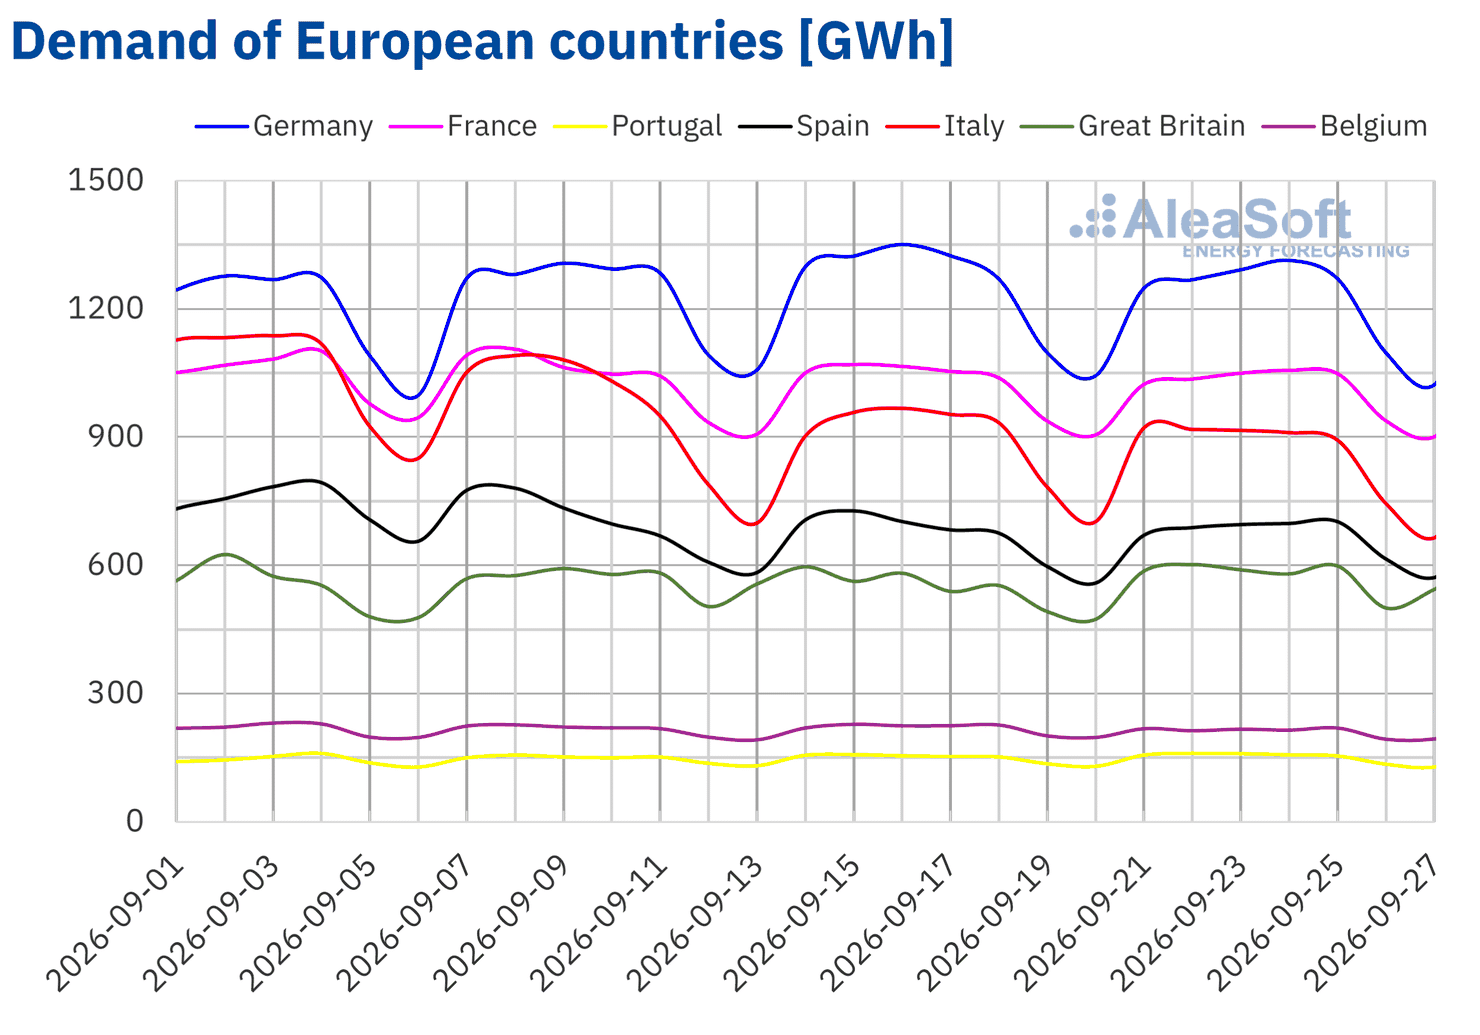 Source: Prepared by AleaSoft Energy Forecasting using data from ENTSO-E, RTE, REN, Red Eléctrica, TERNA, National Grid and ELIA.
European electricity markets
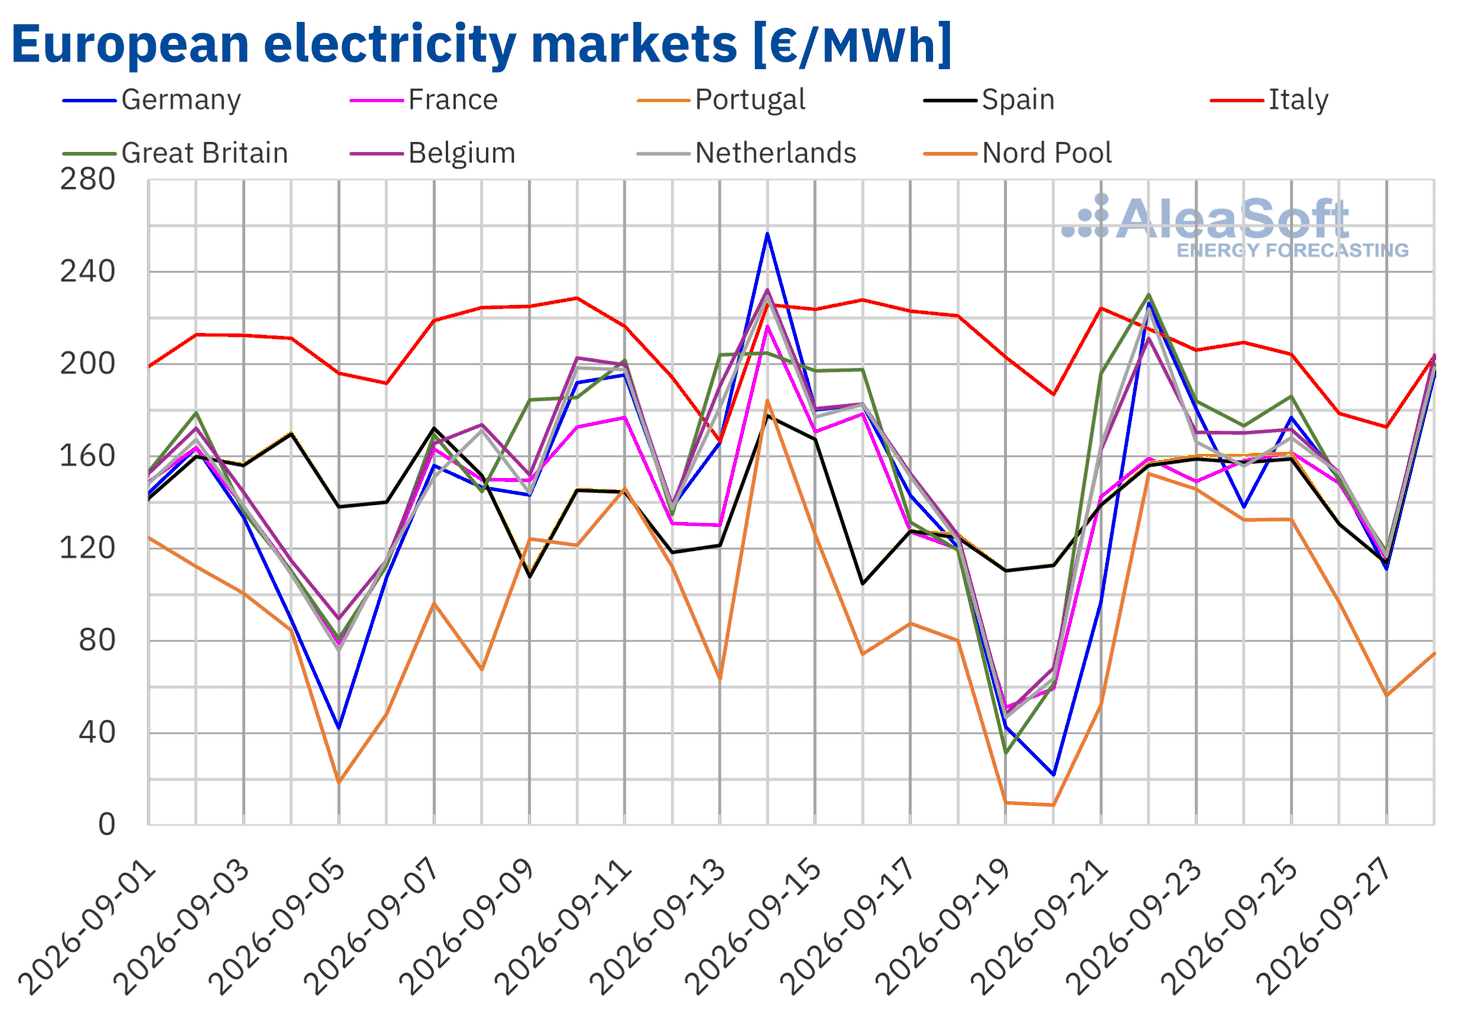
Weekly average prices rose in the major European electricity markets in the fourth week of September, except in Italy. The Nordic market registered the largest increase, at 35%, followed by the British market, with a 31% rise. Prices also increased by 18% in the Netherlands, 17% in Belgium, 14% in Germany and 12% in France. Spain and Portugal registered the smallest increases, at 9.7% and 10%, respectively. In contrast, prices in the Italian market fell by 6.7%.
Despite the decline, the Italian market once again registered the highest weekly average, at €201.47/MWh, while the Nordic market had the lowest, at €109.72/MWh. In the other markets analyzed at AleaSoft Energy Forecasting, weekly average prices ranged from €144.87/MWh in Spain to €176.70/MWh in the British market.
Regarding daily prices, most markets reached their highest prices of the week on Tuesday, September 22. On that day, the British market registered €230.16/MWh, the highest price of the week among the markets under analysis and its highest price since January 23, 2025. The German and Dutch markets exceeded €220/MWh, reaching €226.18/MWh and €223.94/MWh, respectively, while the Belgian market reached €211.18/MWh. The Italian market registered its weekly peak of €224.23/MWh on Monday, September 21, and remained above €200/MWh from Monday through Friday. The French, Portuguese and Spanish markets reached their highest prices of the week on Friday, September 25, at €161.52/MWh, €161.38/MWh and €158.92/MWh, respectively.
Meanwhile, the Nordic market registered the lowest price of the week among the markets under analysis, at €52.11/MWh, on Monday, September 21. On Sunday, September 27, prices fell in all markets compared to the previous day. That day, the French, Portuguese, Spanish, British, Belgian and Dutch markets registered their weekly lows, ranging from €113.65/MWh in Spain to €118.54/MWh in the British market. However, on Sunday, the Nordic market had the lowest price, at €56.07/MWh.
Lower wind energy production in most markets contributed to higher prices despite the decline in gas prices. In Great Britain and Portugal, rising demand also contributed to the increases. In contrast, higher wind energy production and lower demand pushed prices down in Italy.

AleaSoft Energy Forecasting’s price forecasts indicate that prices will rise in most European electricity markets under analysis during the week of September 28. In contrast, prices will fall in the Italian and British markets.
 Source: Prepared by AleaSoft Energy Forecasting using data from OMIE, RTE, Nord Pool and GME.
Brent, fuels and CO2
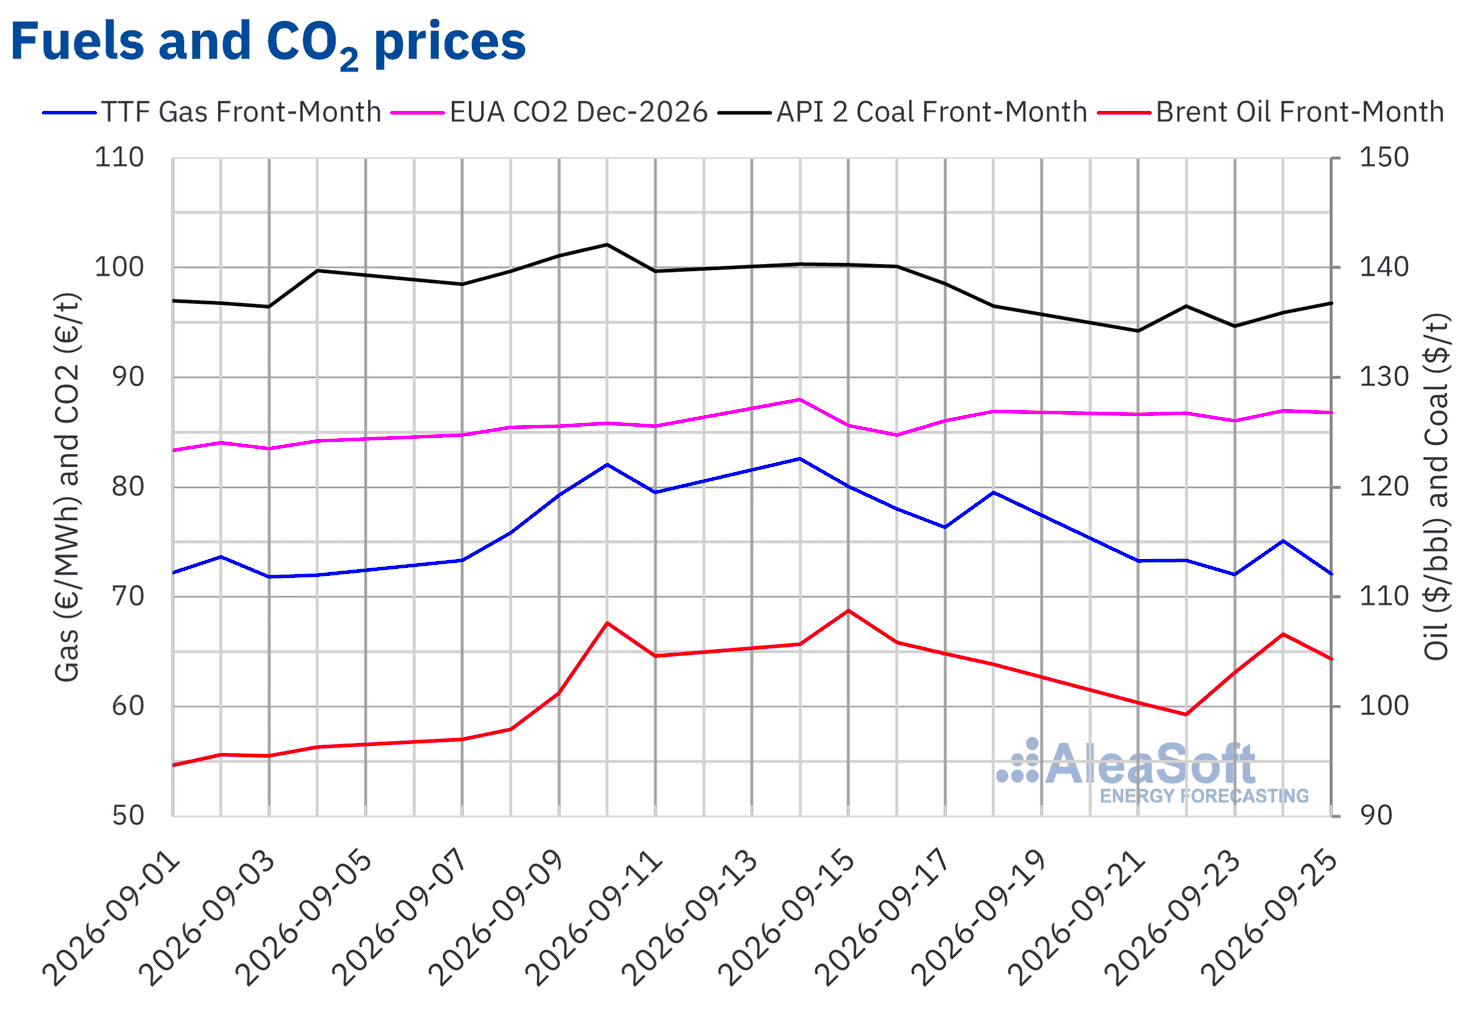
Brent oil futures for the Front‑Month in the ICE market registered their weekly minimum settlement price, at $99.25/bbl, on Tuesday, September 22, after five consecutive sessions of declines. According to data analyzed at AleaSoft Energy Forecasting, this was the lowest price since September 9. Prices subsequently rose, reaching their weekly maximum settlement price of $106.60/bbl on Thursday, September 24. On Friday, September 25, the settlement price stood at $104.32/bbl, 0.4% higher than on the previous Friday.
At the beginning of the week, the US president’s offer to meet with the Iranian president at the United Nations General Assembly contributed to lower prices. However, the Iranian president’s refusal to surrender to the United States pushed prices higher on September 23. The following day, Yemen’s Houthis launched missiles at Saudi Arabia, while a senior Iranian military official warned that Iran could extend the war to the Indian Ocean if another country attacked it. These developments pushed prices to their weekly high. On Friday, Iran’s proposal for an interim agreement that would include reopening the Strait of Hormuz within seven days contributed to lower prices.
As for TTF gas futures in the ICE market for the Front‑Month, they registered a settlement price of €73.25/MWh on Monday, September 21, 7.9% below the previous Friday’s level. On September 23, they reached their weekly minimum settlement price of €72.01/MWh. According to data analyzed at AleaSoft Energy Forecasting, this was the lowest price since September 5. On Thursday, September 24, prices rose by 4.3% and reached their weekly maximum settlement price of €75.11/MWh. On Friday, September 25, the settlement price stood at €72.07/MWh, 9.4% below the previous Friday’s level.
Talks between the United States and Iran on gradually reopening the Strait of Hormuz, along with an increase in the number of ships using alternative routes, contributed to lower gas prices. However, European Union gas storage levels stood at around 70% of capacity, below the seasonal average for the past five years.
Regarding CO2 emission allowance futures in the EEX market for the reference contract of December 2026, settlement prices remained above €86/t throughout the fourth week of September. On September 23, they registered their weekly minimum settlement price of €86.03/t. The following day, Thursday, September 24, they reached their weekly maximum settlement price of €86.97/t. On Friday, September 25, the settlement price stood at €86.79/t, 0.1% below the previous Friday’s level.
 Source: Prepared by AleaSoft Energy Forecasting using data from ICE and EEX.
AleaSoft Energy Forecasting’s analysis on the prospects for energy markets in Europe
On Thursday, October 15, AleaSoft Energy Forecasting will hold the 70th edition of its monthly webinar series. Deloitte will once again participate in the October webinar, marking its seventh consecutive year at this event. The session will examine recent developments in the major European energy markets and their prospects for the winter of 2026‑2027, as well as financing for renewable energy and storage projects, the prospects for batteries and hybridization, and the role of forecasts in financing, audits and portfolio valuation. The speakers will include Jaume Pujol Benet, Partner, Financial Advisory at Deloitte, Álvaro Antón Azcoiti, Director, Corporate Finance Energy at Deloitte, Ricardo Benito Pascual, Director, Corporate Finance Energy at Deloitte, Álvaro Osés Lainez, Manager, Treasury Advisory at Deloitte, and Oriol Saltó i Bauzà, Associate Partner at AleaSoft. Antonio Delgado Rigal, founder and CEO of AleaSoft, will moderate the Spanish‑language webinar. Alejandro Delgado Fornaguera, Associate Partner at AleaSoft, will moderate the English‑language webinar.
Source: AleaSoft Energy Forecasting.